The short answer: what to bring
The setup that works: two cards on two different networks (ideally one Visa, one Mastercard), at least one with no foreign transaction fee. Add a phone with a contactless wallet and enough VND cash for one to two days.
Three rules save the most money. Always pay in VND, never accept conversion to your home currency. Never use a credit card at an ATM. Ask about the surcharge before you tap at a hotel or tour desk.
Everything else in this guide is detail on top of that.
How Vietnam actually pays: cash, cards and QR codes
Where cards are accepted
Cards work reliably at hotels from mid-range up, malls and supermarkets (WinMart, Lotte Mart, Aeon, Co.opmart), convenience chains (Circle K, GS25, FamilyMart, 7-Eleven in the south), coffee chains (Highlands, Phuc Long, Starbucks), airlines, cinemas, larger restaurants, ride-hailing apps paid in-app, and many tour desks.
Where cash is still king
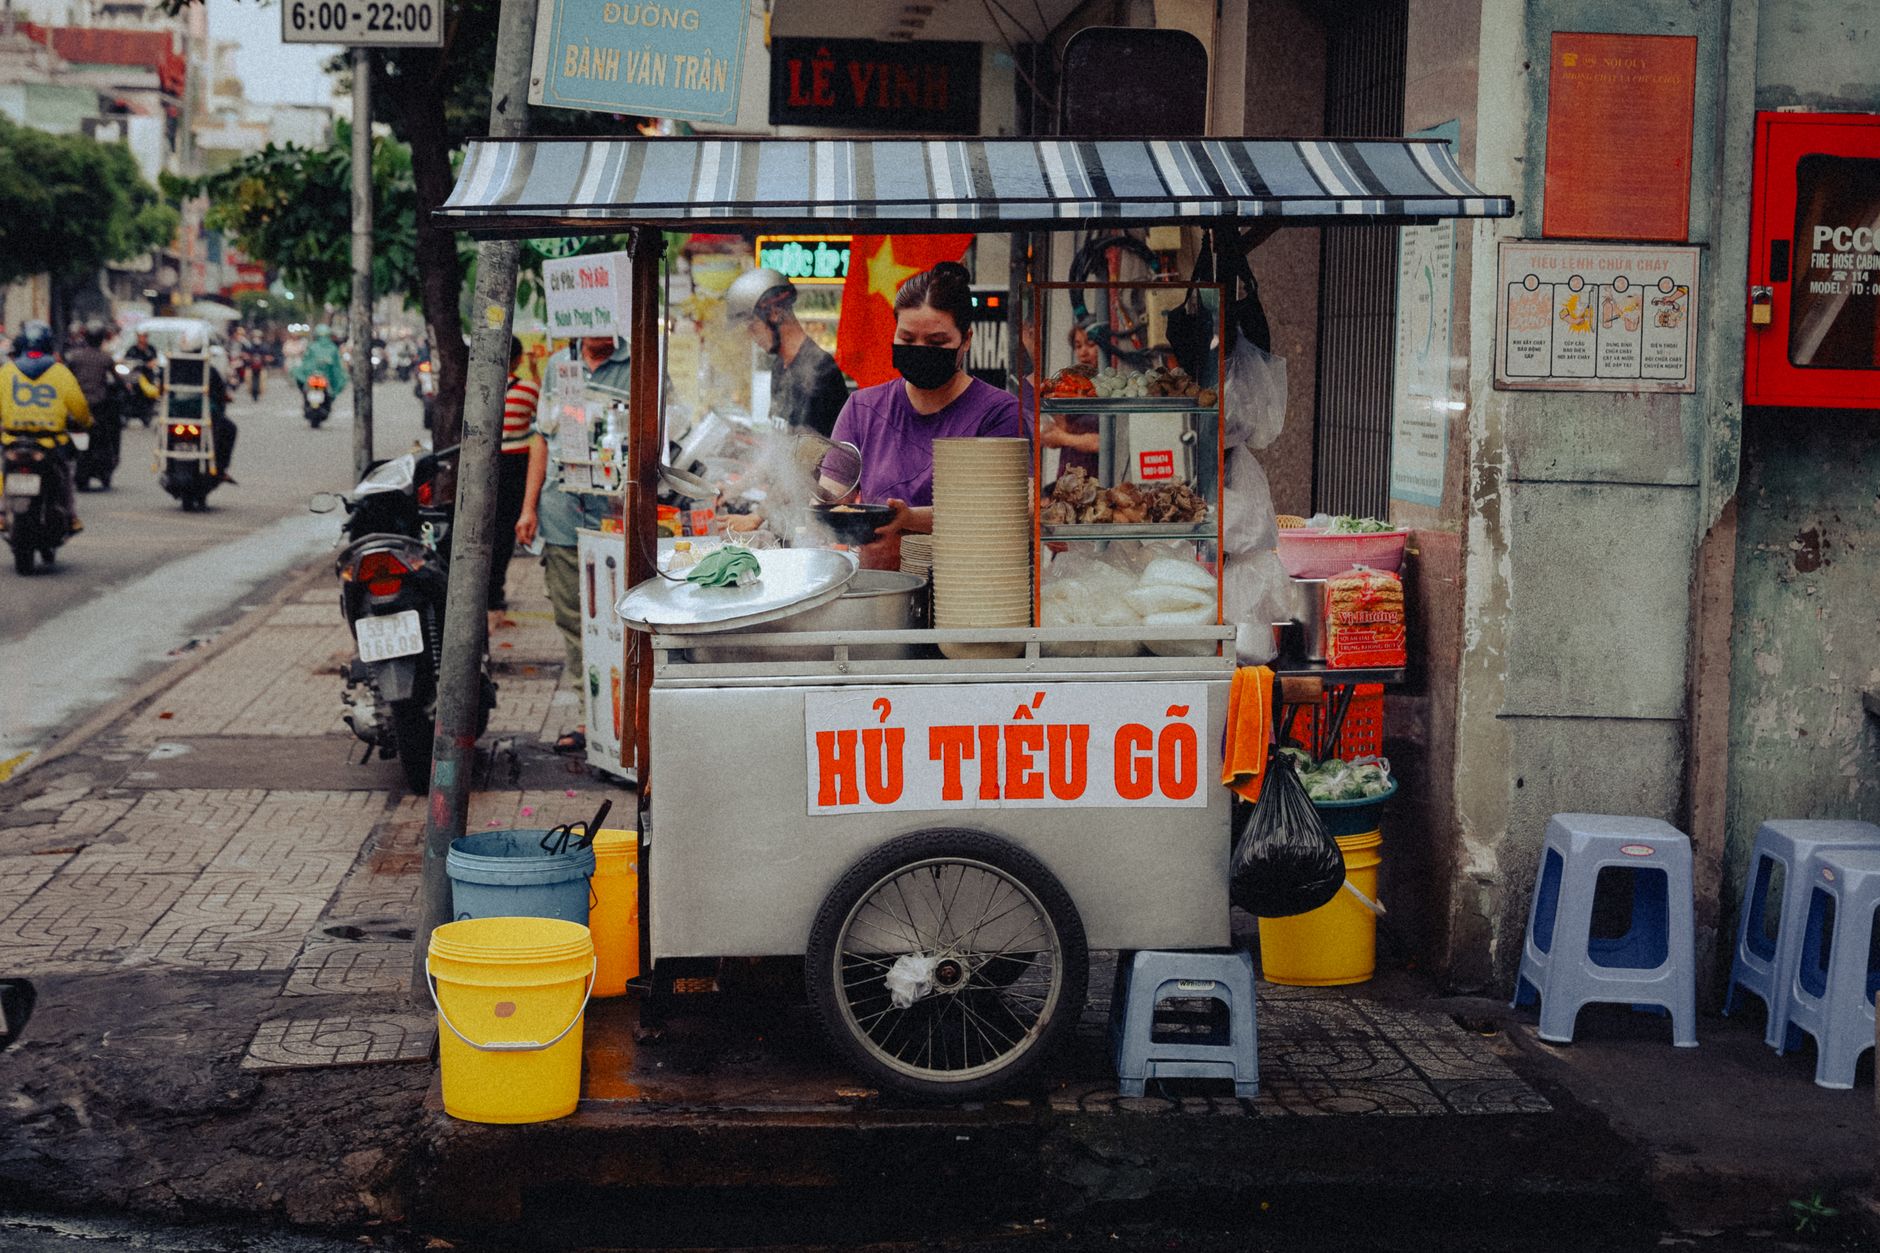
Cash is expected at street food stalls, markets and sidewalk cafés, xe om motorbike taxis hailed on the street, local buses, small guesthouses and homestays, entrance fees at small pagodas and villages, parking attendants, toilets and tips. Most of the northern mountains (Ha Giang loop, Cao Bang) and rural Mekong areas run almost entirely on cash.
The QR code revolution and why it mostly excludes tourists
VietQR, the Napas standard, is now everywhere, including bánh mì carts. It normally requires a Vietnamese bank account or e-wallet. That is why a vendor may wave you off with a QR sign and still expect cash. Cross-border QR links with neighbouring countries and partner networks such as Alipay+ are expanding, but coverage for a European or American phone is still patchy. Check your own banking app's list of supported countries before you rely on it.
Regional reality check
- Hanoi, Ho Chi Minh City, Da Nang: card-friendly, but daily life still runs on cash and QR.
- Hoi An, Nha Trang, Phu Quoc: card-friendly in tourist businesses, where surcharges are common.
- Sapa, Ninh Binh, Ha Giang, Con Dao: cash-dependent. ATMs exist in towns but not in villages.
| Place type | Cash | Card | Contactless | VietQR | Surcharge likely? |
|---|---|---|---|---|---|
| Street food, market stall | Yes | No | No | Yes (local accounts) | No |
| Coffee chain | Yes | Yes | Yes | Yes | No |
| Convenience store | Yes | Yes | Yes | Yes | No |
| Mid-range hotel | Yes | Yes | Yes | Yes | Often 2 to 3% |
| Homestay, small guesthouse | Yes | Rarely | Rarely | Sometimes | No |
| Grab or ride-hailing | No | In-app | In-app | No | No |
| Tour desk, tailor, dive shop | Yes | Yes | Yes | Sometimes | Often 2 to 4% |
| Small pagoda, village fee | Yes | No | No | No | No |
Card networks in Vietnam: Visa, Mastercard, JCB, Amex, UnionPay and the rest
| Network | Merchant acceptance | ATM acceptance | Typical surcharge | Notes |
|---|---|---|---|---|
| Visa | Near-universal where cards are taken | Wide | Standard | Safest default |
| Mastercard | Near-universal | Wide | Standard | Safest default |
| JCB | Good in tourist and Japanese-frequented areas | Good | Standard | Useful second card for Japan-based travellers |
| UnionPay | Many merchants serving Chinese visitors | Many (Vietcombank, BIDV, Agribank) | Standard | Useful for China, Hong Kong, Taiwan |
| American Express | International hotels, airlines, upscale venues | Limited | Often higher | Carry a Visa backup |
| Discover, Diners Club | Rare | Rare | n/a | Do not rely on it |
| RuPay | Limited | Limited | n/a | Bring Visa or Mastercard instead |
| Mir | Not accepted | Not accepted | n/a | No workaround with a Mir card |
One point that published sources often get wrong: perks belong to the issuing bank, not the network. Cashback, lounge access and insurance come from your card issuer's terms, not from "Visa" or "UnionPay" in general.
Old European debit brands also fail here. V Pay works only in Europe. Maestro is being phased out (Mastercard stopped new European issuance from July 2023). Older German girocard cards co-badged with V Pay or Maestro may simply be declined in Vietnam.
Contactless, mobile wallets and QR payments for visitors
Tap to pay with a foreign card or phone
Apple Pay launched for Vietnamese-issued cards in August 2023, and contactless terminals are now standard in chains. A foreign Visa or Mastercard loaded into Apple Pay or Google Pay works on any contactless terminal, because the payment simply runs through the card network. Small taps may skip the PIN. Larger amounts may require inserting the card.
MoMo, ZaloPay, VNPay and why they are hard for short-stay visitors
These apps generally need a Vietnamese phone number, eKYC verification and a linked local bank account or card. Some have experimented with foreign-card top-ups for tourists, but availability changes. Do not plan your trip around getting one working.
Cross-border QR links
Vietnam has launched or announced QR payment linkages with several neighbouring countries, and partner networks such as Alipay+ let some Asian wallets pay at participating Vietnamese merchants. Which links are live changes month to month. As of October 2026, check your own banking app's supported-countries list before you fly, and treat any vendor sticker as valid only if your app shows Vietnam.
The fees that actually cost you money
Foreign transaction fees charged by your bank
These are typically about 3% in the US and Australia, 2.75 to 2.99% in the UK, 1.5 to 3% plus a fixed fee per payment at many eurozone high-street banks, about 3.5% plus 18% GST on the markup in India, and about 1.6 to 2.2% on Japanese cards.
Merchant card surcharges
Surcharges of 2 to 3%, sometimes 4%, are common at hotels, travel agencies, tailors in Hoi An, dive shops, spas and some restaurants. Amex often attracts a higher rate. Vietnamese card regulations have long been read as prohibiting merchants from charging cardholders extra, and the current circular replaced the 2016 rules, but the exact wording should be checked before you quote it as law. In practice, surcharging is widespread and arguing rarely works.
Ask before paying. Compare the card total with the cash price. For a large surcharged bill, it can be cheaper to withdraw cash at a low-fee ATM and pay in notes, if the maths works out.
ATM operator fees
Vietnamese banks typically charge foreign cards per withdrawal, reported at roughly 20,000 to 110,000 VND (0.80 to 4.20 USD), on top of any fee from your home bank. Fee policies change frequently, so verify against current bank tariffs rather than a list you found online.
Dynamic currency conversion
The terminal or ATM offers to charge you in your home currency at its own rate. Markups of roughly 3 to 7% over the reference rate are commonly reported. The EU's DCC disclosure rules apply only inside the EEA, not in Vietnam. Always choose VND.
Credit card cash advances
Withdrawing cash with a credit card usually triggers a cash advance fee and interest from day one, even on cards with no foreign transaction fee.
Neobank fine print
Free ATM allowances run out. Some plans add a weekend FX markup. Monthly fair-use limits on currency exchange exist. Read the plan details before you rely on them.
| Fee | Who charges it | Typical size | When it appears | How to avoid |
|---|---|---|---|---|
| Foreign transaction fee | Your bank | 1.5 to 3.5% | Every card payment abroad | Use a no-FTF card |
| Merchant surcharge | The business | 2 to 4% | Hotels, tour desks, tailors | Ask first, compare with cash |
| ATM operator fee | Vietnamese bank | 20,000 to 110,000 VND | Each withdrawal | Withdraw the maximum each time |
| DCC markup | Terminal or ATM operator | 3 to 7% | When offered home currency | Always choose VND |
| Cash advance | Your card issuer | Fee plus interest | Credit card at ATM | Use a debit card |
Double conversion: how it happens and how to avoid it
Four scenarios account for most of the money lost.
- DCC at a terminal or ATM. VND is converted to EUR at the merchant's rate, and your bank may still apply its own fee.
- Prepaid travel cards without VND. The card holds USD, GBP or EUR and spends from a USD wallet in Vietnam, so you go EUR to USD to VND. Many fixed-currency prepaid cards do not offer VND as a loadable currency.
- Prices quoted in USD by hotels and tour operators. The hotel converts USD to VND at its own rate, then your bank converts VND to your home currency.
- Booking platforms charging in USD. Booking with a card in AUD or KRW creates a hidden conversion. Choose to pay in your card's currency on the platform only if the platform's rate beats your card's, or choose VND or local pricing where offered.
A worked example. Take a 10,000,000 VND hotel bill (about 385 USD at 26,000 VND to the dollar). Pay with DCC at a 5% markup, add a 3% merchant surcharge, then a 2.99% bank fee, and the overpayment passes 30 USD. Pay the same bill in VND with a no-FTF card and no surcharge, and you save that entire amount.
Which card to bring, country by country
Examples below are as of October 2026. Check the issuer's fee page before you fly, because products get withdrawn and terms change.
United States
Many credit cards charge about 3%, though no-FTF cards are common. Capital One's cards and travel cards from Chase and Amex are typical examples. Amex acceptance in Vietnam is limited, and Discover acceptance is rare. Note Capital One's 2025 acquisition of Discover and possible network changes. For cash, some debit cards refund foreign ATM fees (Charles Schwab's checking account is widely cited). Watch for accounts that refund ATM fees but still charge a foreign transaction fee.
Canada
Most cards charge about 2.5% FX. A minority of credit cards and some fintech prepaid cards waive it. Check that any product you find is still open to new applicants.
United Kingdom
High-street debit cards typically charge 2.75 to 2.99% plus a per-transaction fee. App banks such as Starling, Chase UK and Monzo, and some credit cards (Barclaycard Rewards is often cited), waive FX fees. Watch ATM allowances and interest on credit card cash withdrawals.
Ireland
Traditional bank debit cards carry high non-euro fees. App banks are the usual workaround.
France
Traditional banks charge about 2 to 3% plus fixed fees per payment and withdrawal outside the eurozone. Online banks such as Boursorama and Fortuneo offer cards that waive these fees on payments and some withdrawals. Check whether your card requires an international or premium tier.
Germany
A girocard co-badged with V Pay will not work. Bring a Visa Debit, a Debit Mastercard or a credit card. Several direct banks and credit card issuers offer no-FX-fee cards, sometimes with conditions such as "active customer" status.
Spain and Italy
Traditional banks usually charge FX fees. Neobanks and online banks dominate the no-fee space. In Italy, check whether old cards are Maestro or V Pay before you rely on them.
Netherlands and Belgium
Banks often geo-block card use outside Europe by default, so you must switch the card to "world" in the app before flying. Dutch banks replaced Maestro with Visa or Mastercard debit, but still apply an FX markup and ATM fees outside the EU.
Australia and New Zealand
Big-four banks charge about 3%. Several credit cards and transaction accounts waive FX fees, some with monthly conditions. Check whether long-recommended products are still open to new applicants.
South Korea
Standard cards charge a network fee plus an issuer overseas fee. Since 2024, bank travel debit cards with pre-loaded foreign currency and free overseas ATM withdrawals have become mainstream (Hana Travelog, Shinhan SOL Travel and similar). Check whether VND can be pre-loaded. If not, spending runs from a USD wallet and becomes a double conversion. Some Korean wallets have partner-network acceptance in Vietnam, but verify the date before relying on it.
Japan
Overseas admin fees are typically about 1.6 to 2.2%. JCB is relatively well accepted in tourist areas. Multi-currency debit cards from Japanese banks usually do not hold VND, so the standard fee applies.
India
The forex markup is typically about 3.5% plus 18% GST on the markup. Low- or zero-markup credit cards and zero-markup debit and forex products exist. RuPay acceptance is limited, so bring a Visa or Mastercard. Under the Liberalised Remittance Scheme, tax collected at source applies to debit and forex card spending above the annual threshold (raised to 10 lakh rupees from April 2025), while international credit card spending was kept outside TCS. Verify current rules. Most Indian forex cards cannot load VND.
Singapore, Thailand, Malaysia and other ASEAN countries
Local multi-currency cards are popular in Singapore. Check the cross-border QR link between your country and Vietnam in your banking app.
China, Hong Kong and Taiwan
UnionPay is accepted at many ATMs and some merchants. Alipay and WeChat Pay are accepted at merchants catering to Chinese visitors.
Russia
Russian-issued Visa and Mastercard cards do not work abroad, and Mir is not accepted in Vietnam. Reports on Russian-issued UnionPay cards abroad are inconsistent. Carry USD or EUR, exchange at licensed banks, and declare cash above 5,000 USD on arrival.
| Country | Typical high-street FX fee | Card types that avoid it | Network to bring | Local watch-out |
|---|---|---|---|---|
| US | About 3% | No-FTF credit cards | Visa, Mastercard | Amex and Discover weak |
| Canada | About 2.5% | Select credit and fintech cards | Visa, Mastercard | Check product still open |
| UK | 2.75 to 2.99% plus fee | App banks, some credit cards | Visa, Mastercard | ATM allowance limits |
| France | 2 to 3% plus fixed fees | Online banks | Visa, Mastercard | Premium tier may be required |
| Germany | Varies | Direct banks | Visa Debit, Debit Mastercard | Girocard with V Pay fails |
| Netherlands, Belgium | FX markup outside EU | Neobanks | Visa, Mastercard debit | Geo-block on by default |
| Australia, NZ | About 3% | Select credit and transaction accounts | Visa, Mastercard | Product eligibility changes |
| South Korea | Network plus issuer fee | Bank travel debit cards | Visa, Mastercard | VND may not pre-load |
| Japan | 1.6 to 2.2% | Some multi-currency cards | JCB, Visa | VND rarely loadable |
| India | 3.5% plus GST | Zero-markup cards | Visa, Mastercard | RuPay limited, no VND load |
| China, HK, Taiwan | Varies | Multi-currency cards | UnionPay, Visa | Alipay only at some merchants |
| Russia | n/a | n/a | None reliable | Bring cash, declare above 5,000 USD |
Neobanks, multi-currency accounts and prepaid travel cards
How multi-currency accounts and neobank cards price VND
Expect mid-market or near-mid-market conversion with a small fee, free ATM allowances (often a few withdrawals or about 200 units of home currency a month on basic plans), and weekend markups on some plans. Whether VND can be held as a balance differs by provider and plan, so check inside the Wise and Revolut apps rather than trusting a blog post.
Prepaid travel cards
Useful for budgeting and for separating funds from your main account. Their weakness is the lack of VND loading, which creates double conversion. A few once-recommended providers no longer operate, so check that any product you mention still exists.
Neobank vs. traditional card
Neobanks offer better rates. Traditional cards offer higher limits, stronger chargeback support, phone support and easier hotel pre-authorisations. Carry one of each.
Virtual cards for online bookings
Virtual cards reduce fraud exposure when booking domestic flights, trains or tours online.
| Product type | How VND is priced | Can hold VND? | Free ATM allowance | Weekend markup | Best use |
|---|---|---|---|---|---|
| Neobank card | Near mid-market plus small fee | Usually no | A few withdrawals a month | On some plans | Everyday spending |
| Multi-currency account | Near mid-market | Sometimes | Varies | Sometimes | Long trips |
| Prepaid travel card | Via USD or EUR wallet | Rarely | Varies | Sometimes | Budgeting |
| Traditional credit card | Bank rate plus FX fee | No | n/a | No | Big purchases, backup |
ATMs and cash: withdrawing, exchanging and how much to carry
Using Vietnamese ATMs
Prefer machines attached to bank branches, used during opening hours. Per-transaction limits are typically 2,000,000 to 5,000,000 VND (about 77 to 192 USD), with some banks allowing up to 10,000,000 VND (about 385 USD). Decline any conversion offer. If a machine swallows your card, contact the branch the same day with your passport.
Exchanging cash
Use licensed banks and authorised exchange counters, including airports, where you should compare rates. Some guides recommend gold shops, but exchanging at unauthorised places is technically illegal for the customer, and fines have been imposed. Pricing in foreign currency is also prohibited, even though some businesses still quote USD.
Cash rules and banknote traps
Declare cash above 5,000 USD equivalent or 15,000,000 VND on entry. Notes run from 1,000 to 500,000 VND. There is no 5,000,000 VND note, despite claims in some published sources. Coins are no longer issued and are rarely seen. Confusing 10,000 with 200,000, or 20,000 with 500,000, is a classic mistake.
How much cash to carry
A budget traveller can get by on 500,000 to 800,000 VND (about 20 to 30 USD) a day in cash, with cards covering hotels. A mid-range traveller should carry 1,500,000 to 2,500,000 VND (about 58 to 96 USD) for meals, transport, tips and small entries. Double it in the mountains.
Holidays when ATMs run dry
Around Tet, banks close for several days and ATMs in smaller towns can empty. The next Tet falls on 6 February 2027. Withdraw beforehand and check the official 2027 holiday schedule. The 30 April to 1 May break and 2 September National Day also bring closures and crowds.
Before you fly: the payment checklist
- Turn on international use and remove any geo-block in your banking app.
- Check expiry dates on every card you pack.
- Raise ATM and spending limits before departure.
- Save your bank's emergency number in a format that does not depend on your phone.
- Split cards between bags, and keep one card separate from your wallet.
The OTP trap: online payments in Vietnam (domestic flights, trains, some apps) use 3-D Secure, often by SMS to your home number. If you swap to a Vietnamese SIM or eSIM and lose your home line, you cannot receive codes. Keep the home line active on a dual SIM or eSIM, or switch to in-app approval before departure.
Hotel pre-authorisation holds on debit cards can take 7 to 30 days to release. Use a credit card for hotel check-in where possible.
Safety, fraud and what to do when things go wrong
Real risks include ATM skimming, cards taken out of sight, inflated totals keyed into terminals, and DCC pushed by staff.
If a card is lost or stolen, freeze it in the app, call the issuer and file a police report if insurance requires it. If it is blocked, a false fraud alert on the first Vietnamese transaction is common, so approve it in the app. If a machine swallows it, visit the bank branch that owns the ATM.
Some motorbike rental shops hold passports as a deposit. Offer a cash deposit instead, and never leave a card imprint without a written amount.
Staying longer: Vietnamese bank accounts and e-wallets
For expats and digital nomads, opening a local account typically requires a passport, a visa of sufficient length and sometimes a temporary residence card. Biometric verification rules introduced in 2024 apply to online transfers and app access. A local account unlocks VietQR, MoMo and domestic-only websites. Policies vary by branch, so ask ahead.
FAQ
Q: Is a credit card widely used in Vietnam? Yes in hotels, malls, chains, airlines and ride-hailing apps, especially in Hanoi, Ho Chi Minh City and Da Nang. Everyday local commerce still runs on cash and Vietnamese QR codes. Plan to pay about half your spending in cash on a typical itinerary, and more in the mountains and rural areas.
Q: Can I use a Revolut or Wise card in Vietnam? Yes, because they are Visa or Mastercard cards and work at terminals and ATMs. Watch the free ATM allowance, weekend markups on some plans and the local ATM operator fee. Carry a second card from a different provider as backup.
Q: Do I need a digital card or mobile wallet for Vietnam? No. A physical chip-and-PIN Visa or Mastercard is enough. Adding it to Apple Pay or Google Pay is convenient for contactless payments. Local wallets such as MoMo and ZaloPay usually require a Vietnamese account, and a virtual card is useful for online bookings.
Q: Should I pay in VND or in my home currency when the terminal asks? Always VND. Choosing your home currency triggers dynamic currency conversion at the merchant's rate, which typically costs several percent more. The same applies at ATMs.
Q: Why do shops add 2 to 3% when I pay by card, and can I refuse? Surcharges are common at hotels, agencies and tourist businesses, even though Vietnamese card rules are generally read as prohibiting them. Ask before paying, compare with the cash price, and decide which works out cheaper.
Q: Can I pay in US dollars in Vietnam? Pricing and payment in foreign currency are prohibited for most businesses, although some hotels and agencies quote USD. Paying in USD usually means a poor conversion rate, and VND is almost always cheaper.
Q: Which ATMs are cheapest for foreign cards? Fees and limits change often. Withdraw the maximum each time to spread the fixed fee, use branch-attached machines, and never withdraw cash with a credit card. Check current bank tariffs rather than a list you found online.
Q: Is 100 USD a lot of money in Vietnam? At about 26,000 VND per USD (check the rate on the day), 100 USD is about 2,600,000 VND. That covers several days of street food and local transport, or roughly one day of mid-range travel with a hotel, meals and a tour.
Your questions and tips
A question, an update, an experience to share? Our team reads every message before it is published.
No comments yet. Ask the first question or share a tip!